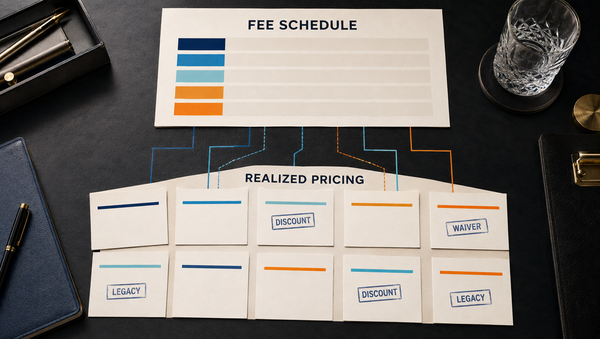
Most wealth management firms can produce a fee schedule in minutes. It shows the pricing architecture the firm intends to apply: tiers, breakpoints, programs, service levels and approved ranges.
The economics of the installed book are harder to see. Realized pricing is shaped over time by householding, negotiated discounts, inherited arrangements, waivers, temporary concessions, acquisition history and one-off exceptions. The result can be a meaningful gap between the price a firm designed and the price it actually earns.
That gap is not automatically a problem. Wealth management is a relationship business, and variation can be commercially sound. The management issue begins when leaders cannot explain why similar relationships are priced differently, whether the rationale still holds, or which relationships deserve attention.
Recent industry research shows why the question matters. Cerulli Associates reported that by 2026, 83% of advisors expected to charge less than 1% for clients with more than $5 million in investable assets, with average pricing around 66 basis points for relationships above $10 million. At the same time, research from Datos Insights reported by InvestmentNews found that 53% of advisors who charge for planning had raised fees in the prior year. Among those fee raisers, 43% changed pricing only for new clients while just 10% applied increases across the full book.
The installed book carries history
A client relationship rarely stays exactly as it was designed on day one. Assets move. Service needs expand. Families consolidate accounts. Advisors make accommodations. Firms acquire books with different pricing logic. Temporary concessions remain in place longer than expected. New pricing is introduced for new households while long-standing clients keep legacy economics.
Each decision can be reasonable in isolation. Across thousands of households, however, the firm can end up with a book where similar relationships produce very different economics and no one can quickly explain why.
This is where a traditional fee schedule reaches its limit. A schedule can tell leaders which rate was permitted. It cannot tell them whether the realized rate still fits the relationship today.
Visibility should come before repricing
The natural reaction to a pricing gap is to ask how much revenue could be recovered. That question matters, but it is not the first one to answer. A disciplined pricing review starts by making the book visible.
- What is the realized rate at the household level after discounts, exclusions and adjustments?
- Which relationships sit materially above or below relevant internal cohorts?
- Which differences are supported by current service scope, household economics or strategic value?
- Which exceptions have an owner, a reason and a review date?
- Where has the original rationale disappeared while the lower price remained?
Once those questions are answerable, pricing variation becomes a management decision rather than a mystery.
A lower price can lead to several different decisions
A lower realized rate does not automatically mean the advisor should raise the fee. A strong pricing process separates diagnosis from action. Depending on the relationship, the right decision may be to maintain and document the existing price, reprice the relationship, change the service scope, migrate the household to a better delivery model, or transition the relationship in a controlled way.
That distinction matters because the goal is not to force every household toward a single rate. The goal is to make pricing variation intentional, explainable and governed.
Small differences can create meaningful economics at scale
The math behind realized pricing becomes material quickly. On $10 billion of relevant billable assets, one basis point is $1 million of annual revenue. On $50 billion, that same basis point is $5 million. Those are arithmetic illustrations, not forecasts, but they show why firms benefit from understanding the distribution of realized pricing before unmanaged variation compounds across the book.
The most useful opportunity estimate is therefore the one built from the firm's own data: actual households, actual advisors, actual rates, actual exceptions and the service context behind them.
The management question is simple
Can the firm see how pricing is actually distributed across the book, explain why comparable relationships differ, and decide consistently what should happen next?
That is the shift from managing a fee schedule to managing pricing performance.
For a deeper framework, read The Price You Set Is Not the Price You Get. To see how PureFacts connects realized pricing, relationship context and advisor actions, explore Practice Management.